Indicative price, tips, grants and companies for your project in Val-de-Travers (Neuchâtel).
At a glance
Typical budget
CHF 7'200 – CHF 15'400
Midpoint
CHF 10'500
Grants found
0
Nearby companies
4
Worked examples in Val-de-Travers
Small project
CHF 4'000 – CHF 9'100
Typical project
CHF 7'200 – CHF 15'400
Large project
CHF 12'400 – CHF 25'400
Project
Quantity
Low
High
Per unit
Small project
5 kWh
CHF 4'000
CHF 9'100
CHF 1'200
Typical project
10 kWh
CHF 7'200
CHF 15'400
CHF 1'100
Large project
18 kWh
CHF 12'400
CHF 25'400
CHF 1'000
Computed with our estimator for Val-de-Travers (regional factor included), standard finish. Only the project size changes.
Cost split (typical project)
Labour :CHF 2'100(20 %)
Materials :CHF 7'300(70 %)
Other costs :CHF 1'100(10 %)
What the price covers
Included
Supply and installation
VAT
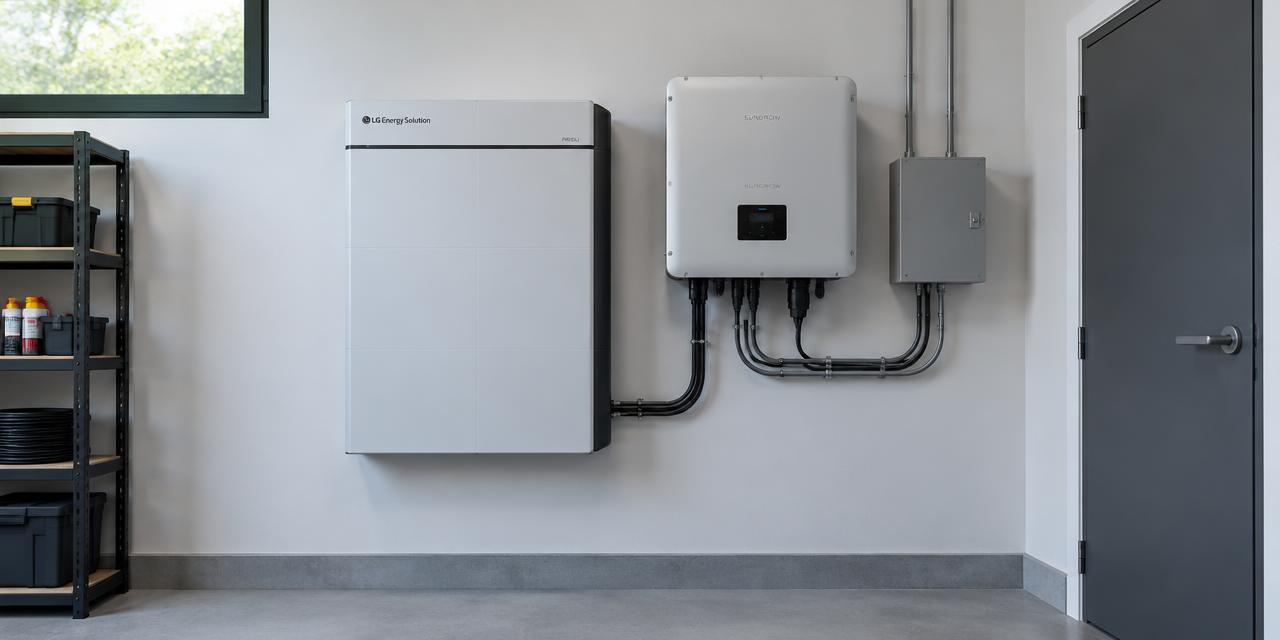
Battery, charge management and standard connection; options according to answers
Not included
Permits and architect fees
Unexpected structural issues
Possible subsidies
Solar panels and complete electrical refurbishment
Tips before you start
A battery is worthwhile when solar output clearly exceeds your daytime use.
Size capacity by evening consumption, not panel power.
Check compatibility with your existing inverter before buying.
Your project in 5 steps
1. Estimate
Set a budget range with the estimator.
2. Grants
Apply before work starts.
3. Quotes
Compare at least 3 quotes.
4. Permit
Check with the municipality whether a permit is needed.
5. Works
Follow the site and do a written handover.
Grants and subsidies
No specific grant listed for this work. Maintenance tax deductions may still apply.
Val-de-Travers's housing stock in figures
The federal building register lists 2'571 residential buildings with 6'097 dwellings in Val-de-Travers. 77% were built before 1980, before serious insulation standards, and 62% are still heated with oil or gas.
Only 12.8% of residential buildings in Val-de-Travers report a solar thermal system in the register, so most roofs are still free. Photovoltaics are not recorded there; check the solar cadastre for your roof.
77 %built before 1980
62 %heated by oil or gas
9.8 %electric hot water
12.8 %with declared solar thermal
Age of residential buildings
Before 191948 %
1919–19457 %
1946–19608 %
1961–19708 %
1971–19806 %
1981–19909 %
1991–20005 %
2001–20104 %
Since 20115 %
Main heating energy
Heating oil38 %
Gas24 %
Heat pump15 %
Wood14 %
District heating7 %
Solar thermal2 %
Heating and hot water: which energies?
Energy
Heating
Hot water
Gas
24 %
20 %
Heating oil
38 %
31.5 %
District heating
7 %
6.3 %
Heat pump
15 %
10.7 %
Electricity
0 %
9.8 %
Wood
14 %
9.6 %
Solar thermal
2 %
12.1 %
Each line gives the share of buildings using that energy, separately for heating and for hot water. The two columns do not always reach 100%: some buildings combine two systems, or reported none.
Type of heating system
Boiler (unspecified)67.2 %
Heat pump14.9 %
Heat exchanger (district)6.9 %
Stove5 %
Condensing boiler3.6 %
A standard non-condensing boiler is usually older and less efficient.
Houses or apartment buildings?
Single-family houses54.7 %
Two-dwelling houses16.8 %
Apartment buildings (3+)28.4 %
Other0.1 %
16.4 % of buildings mix housing with shops or offices.
The typical building
storeys (median)
2
median footprint
162 m²
median dwelling area
90 m²
Renovations, heritage and volumes
For renovation planning in Val-de-Travers, official building register figures show that 5 out of 2571 buildings are protected under heritage status. Owners must consult the municipality early to address permit requirements. Furthermore, with a median house volume of 790 m3 based on 47 units measured via the SIA 416 standard, you can better estimate the scale of heating or insulation upgrades. Please note that data coverage is partial regarding volume measurements, and no specific renovation year data is currently recorded. Utilizing these insights helps you navigate regulatory expectations and project scope for your home improvement effectively.
5
buildings flagged as protected
status known for 71 of 2'571 buildings; check with the municipality
GABU Contrôle SA performs OIBT electrical inspections, certifies solar installations (Pronovo), and verifies EV charging station compliance for homeowners.
swisspro is a company specializing in electrical installations, charging infrastructure for electric vehicles, and intelligent building automation solutions.
Suggestions from the commercial register by distance and activity. Not an endorsement or partnership.
Useful local data
Rules of the canton of Neuchâtel
These rules apply across the whole canton, not only in this town.
Tax deductions
Carry-forward : Seule la part des frais d'investissement destinés à économiser l'énergie et à ménager l'environnement ainsi que les frais de démolition en vue d'une construction de remplacement, qui n'a pas pu être déduite l'année de facturation (année N) car elle aurait engendré un revenu net négatif, peut être reportée sur les deux années fiscales suivantes (N+1 et N+2). Ces frais doivent avoir été intégralement déclarés l'année de leur facturation. Si des frais sont reportés, la déduction forfaitaire n'est pas possible pour l'immeuble concerné pour la période fiscale correspondante. Le droit de reporter est réservé au propriétaire ayant supporté les frais. L'Intendance des impôts détermine d'office les frais reportables.
Flat rate deduction : 10% du rendement brut des loyers ou de la valeur locative (max. 7 200 CHF) si l'âge du bâtiment est inférieur ou égal à dix ans; 20% du rendement brut des loyers ou de la valeur locative (max. 12 000 CHF) si l'âge du bâtiment est supérieur à dix ans. Aucune autre déduction supplémentaire n'est possible avec le forfait. Les propriétaires d'immeubles commerciaux affectés à leur activité indépendante ne peuvent pas opter pour la déduction forfaitaire pour ces immeubles, mais c'est possible pour d'autres immeubles de leur fortune privée.
Maintenance costs : Le/la contribuable peut choisir, lors de chaque période fiscale et pour chaque immeuble, entre la déduction des frais effectifs et la déduction forfaitaire. Les frais effectifs déductibles sont ceux visant à maintenir la valeur de l'immeuble, facturés durant l'année de calcul. Si les dépenses comportent des dépenses d’entretien, d’amélioration et/ou d’économies d’énergie, une répartition par nature est nécessaire selon un catalogue de répartition.
Energy investments : Les investissements destinés à économiser l’énergie et à ménager l’environnement (remplacement d'éléments vétustes ou adjonction d'éléments/installations dans les bâtiments existants) sont déductibles. Ces frais peuvent être reportés sur les deux années fiscales suivantes s'ils n'ont pas pu être déduits intégralement l'année de facturation (N, N+1, N+2).